
Investing ABCs: Growth
Published: 2026-06-26
This is my second post in my foundational knowledge series for investing. This series is for anyone who wants to start investing, but doesn’t know the first thing about how to begin. You don’t need to read this series in order, but you should read and learn all the ABCs before venturing forth to buy investment products.
The Magic of Compound Interest
Money + Time = Magic
Ahhhh, the wonder of compound interest. When I first started saving in a simple savings account, I loved seeing “free money” roll into my account every month in the form of interest. Sure it was less than the cost of a cup of coffee, but it was money that I now had and I hadn’t had to show up to work to earn. This is most peoples first experience with interest. Interest earned on your savings account is money coming in, rather than those high interest charges on your credit cards which is money going out. In a way, interest is a money game of life. Earning interest is winning. Paying interest is losing (usually – read Learning to Think Like Rich People to understand more context).
Compound interest takes winning at money to another level. It is money earned on both your original money AND on the interest you have already earned. This is growth and it is the “magic” of compounding. Over time, your money begins to multiply your wealth exponentially instead of linearly. This is how you win the money game.
Here is a very simple example of compound interest.
You invest $100 at 10% interest and never add any more money.
- Year 1: You make 10% on your $100 = $10 interest. (Total: $110)
- Year 2: You make 10% on your new $110 = $11 interest. (Total: $121) <== Instead of earning the same $10 as year 1, your interest just earned you an extra dollar. Over time, that extra dollar snowballs.
- Year 3: 10% of $121.00 = $12.10 interest (Total: $133.10)
- Year 4: 10% of $133.10 = $13.31 interest (Total: $146.41)
- Year 5: 10% of $146.41 = $14.64 interest (Total: $161.05)
- Year 6: 10% of $161.05 = $16.11 interest (Total: $177.16)
- Year 7: 10% of $177.16 = $17.72 interest (Total: $194.87)
- Year 8: 10% of $194.87 = $19.49 interest (Total: $214.36)
- Year 9: 10% of $214.36 = $21.44 interest (Total: $235.79)
- Year 10: 10% of $235.79 = $23.58 interest (Total: $259.37)
Build a Money Engine
By the time I was 15, I was already keenly aware that my time was finite and that I would have to acquire money to live on by some means. If I just traded my labour for money, i.e. by earning a pay cheque for working 9-5 Monday through Friday, there would be a hard ceiling to how much money I could ever bring in. For example, if I made $37 an hour, for 40 hours a week, that’s a hard cap at $1480 weekly income (Yes, I am ignoring taxes and other stuff that get skimmed off the top of take home pay for simplicity!).
I also dreaded how much time I would have to spend sitting at a desk. Forty hours a week felt like a high price to pay. A better way to win at life would be to build a money engine that makes money for me 24/7/365 through growth, freeing up my time to do as I pleased. I didn’t know it when I was 15, but this is the concept of Financial Independence.
Enter compounding growth. The more you can feed your money engine, the harder compounding can work for you and the faster your wealth will grow.
It’s easiest to see what I mean with a few fun graphs.
Scenario 1: Go to Work Until you Die
Earn $1480 a week for 40 years, but without any savings and, therefore, no compound magic of any sort.
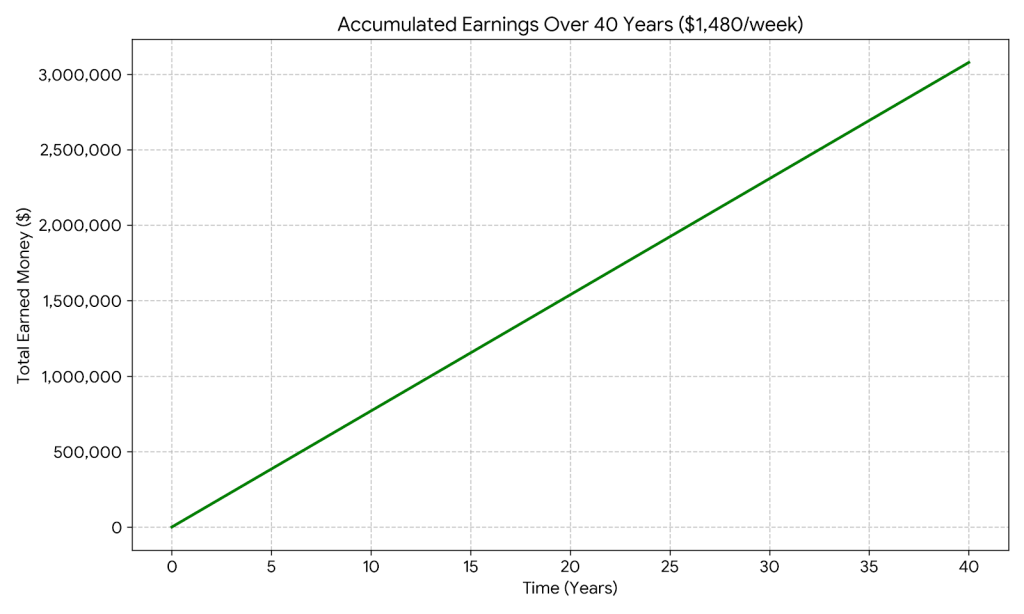
Weekly Earnings: $1,480
Annual Earnings (52 weeks): $1,480 x 52 = $76,960
Total Earnings after 40 Years: $76,960 x 40 = $3,078,400
Over $3 Million is a hefty amount. but, to be clear, this is not your net worth over time. This is not how much you would earn over 40 years at a $37/hr wage. It is how much you traded 4 decades of your life to bring in. Note that the line is straight. This is what not having a money engine looks like.
Scenario 2: Invest 10%
Now let’s add in the magic and assume that we are putting 10% of our earnings, $148 a week, into an investment that grows at 7% annually.
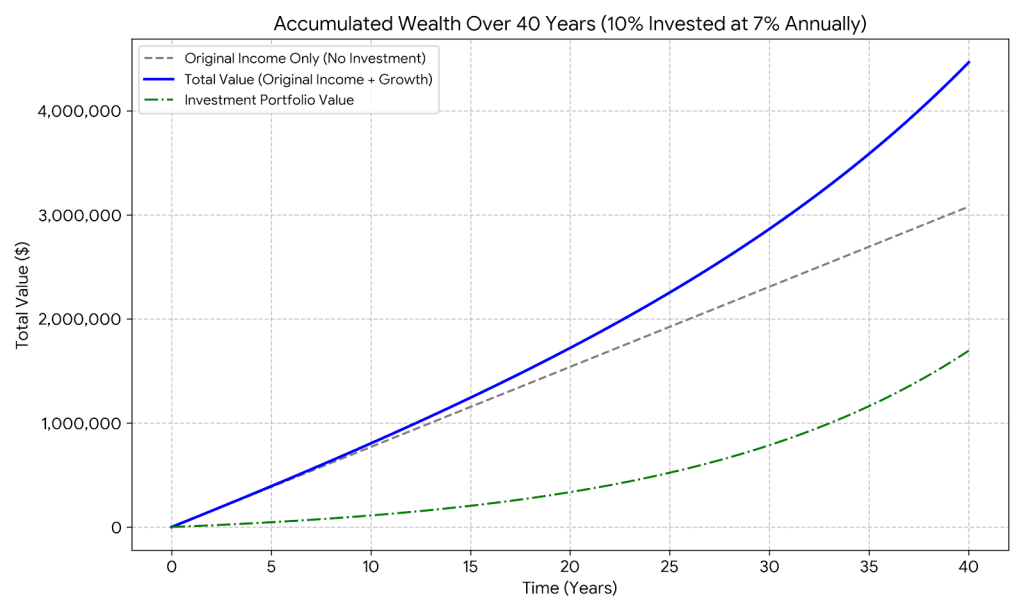
Total Income Earned: Over 40 years, your total gross income remains $3,078,400.
Cash Retained (90%): You keep $1,332 per week for regular spending or savings, which totals $2,770,560.00 over 40 years.
Principal Invested (10%): You contribute $148 per week into the investment, which amounts to a total out-of-pocket contribution of $307,840.00.
$3,078,400.00 (Income from wage) + $1,386,787.52 (Growth Earned) = $4,465,187.52
Notice that our wealth line is starting to curve up! The steeper you can make your line bend, the more growth you have. This is what a working money engine looks like!
Scenario 3: Invest 25%
Finally, let’s assume you follow the MWM Budget and are investing 25% of your take home pay.
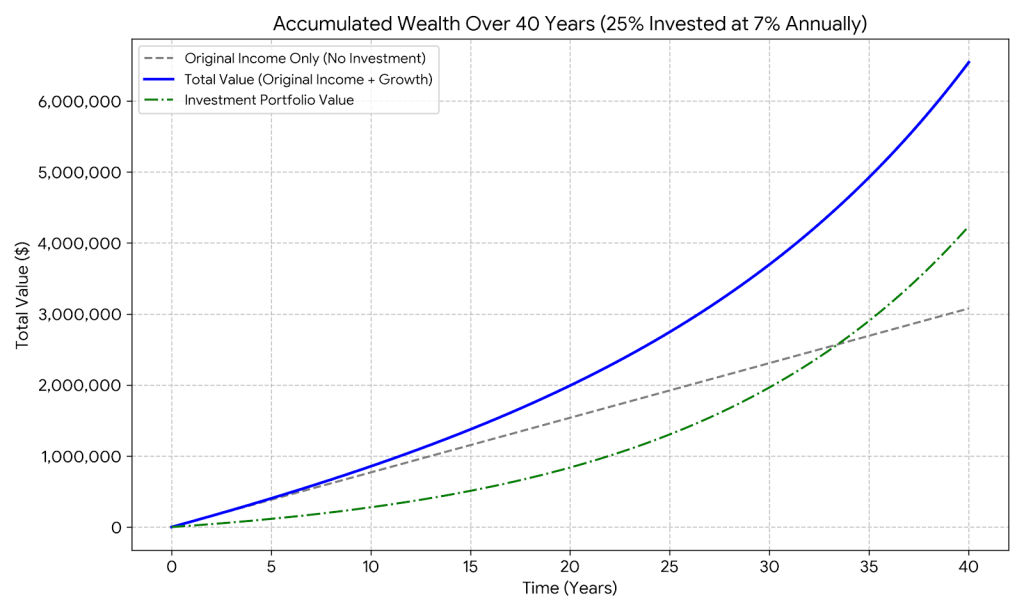
Total Income Earned: Over 40 years, your total gross income remains $3,078,400.
Cash Retained (75%): You keep $1,110 per week for regular spending/savings, which totals $2,308,800.00 over 40 years.
Principal Invested (25%): You contribute $370 per week into the investment, which amounts to an out-of-pocket contribution of $769,600.00.
Total Portfolio Value: Compounding annually at 7%, your investment portfolio grows to an impressive $4,236,568.80
$3,078,400.00 (Income from wage) + $3,466,968.80 (Growth Earned) = $6,545,368.80
Now that is a money engine firing on all cylinders! We have effectively double our earnings over our working lifetime.
One fun thing to note from this chart. Take a look at year 34. Do you see what I see? It’s the point at which the investment portfolio value overtakes the value of your lifetime earned income. This is the moment your money engine is working harder than you are and is what we love to see! If you could invest more money sooner (which would bend your curve even steeper), you could pull that timeline forward and find financial independence sooner.
Comparison Summary
Here is how the three investment rates compare after 40 years:
- 0% Invested: Total earnings of $3,078,400
- 10% Invested: Total earnings of $4,465,187.52$ (Portfolio is $1.69 Million)
- 25% Invested: Total value of $6,545,368.80$ (Portfolio is $4.24 Million)
Why Not Win?
It’s wild to me that more people are not harnessing the power of compound growth through investing. Especially people just entering the workforce. I want to run up to every young person and shake them by the shoulders. They have so much time. They have so much potential. But, sadly, most people do not understand the magic of compounding. It’s not intuitive and honestly, even as someone who’s built a money engine and now depends on it 100% to live, it’s still wild to think about. It still feels like a fairy tale.
But it’s not fantasy, it’s math. And you don’t just have take my word for it; have some fun with an investment calculator and play with your own numbers. How big can you make your money engine?