
Travel Budgeting Tip: Track As You Go
Published: 2026-10-22
In a previous post, I shared with you the system we use to budget for travel.
A quick recap:
- Have a system for vacation savings. For example, move money every month into a seperate account.
- Build a budget for your trip. Decide before you start booking tickets if you can afford the trip you want to take.
- Save up, then spend. Having vacation money saved up before you leave is the best way to skip money stress. No guilt travel is the best travel!
We are currently on the final days of our Sweden trip. I am writing this post from an Airbnb in downtown Copenhagen, sipping my morning coffee, full from a yummy homemade breakfast of eggs and avocado toast. Sadly, I am without my beloved hot sauce, but sometimes you just have to make due when you are on the road.
It’s been a great trip! We reconnected with some old friends, ate and drank our fill, and visited so many cool historical sites.
Living in the moment, I find it’s easy to feel a bit overwhelmed with so much spending. Converting prices on the fly can be a bit tricky and we have been tapping our cards left and right.
Luckily, we keep our cool by sticking to our travel budget. We chose to stay in control by tracking our spending as we go.
Each evening, when we’re back at our accommodations, we take 2 minutes to update our tracking spreadsheet before settling in. We use saved receipts if we paid cash or we use the days transactions from our Wise app if we paid by card.
It only takes a couple of minutes. And it means that we know 100% on a daily basis if we are under or over spent. And, since we know we are under budget, we can enjoy a guilt free final dinner out on our last day before heading home.
If you enjoyed this post, please subscribe to the weekly MWM email.
The Case for Coupons
Published: 2026-10-15
Coupons are awesome.
I’m not talking about the coupons you clip. I don’t actually care much about retail coupons that come by way of flyers or your inbox. I’m talking about a family tradition that we’ve embraced for the almost 30 years.
In my family, it’s incredibly common for us to give each other IOU coupons as gifts.
Coupons have been on my mind thanks to my husband, who has been cashing in a string of IOUs that he’s been hoarding for years.
Why Coupons?
In my family, we celebrate Christmas.
Christmas is a highly commercialized holiday that is heaped in excess. Nestled in between the quant holiday traditions and the family gatherings is pressure to give store bought gifts, entertain, and dress up in fancy clothes. All the festivities are fun, but also lead to overspending, holiday debt hangovers, and over eating.
Enter the humble coupon.
Coupons help us keep it real. They cost time and effort rather than money. They require thoughtfulness and planning. A good coupon is tailored to the recipient. The coupon giver should put intention into their gift.
As a coupon receiver, you get the joy of cashing in the coupon, and you get the gift of anticipation! Part of the joy is planning the perfect time to cash in a coupon. It’s like a gift before the actual gift.
Experiences Over Things
In our early years, even though we didn’t have money to blow, we spent money we didn’t have on gifts.
There is so much social pressure to give stuff to each other. As parents, we definitely felt the pressure to give our kids stuff, some of which was pretty expensive. Most of it ended up broken at the bottom of a toy box. I can remember surveying an entire basement full of toys when my kids were little, wondering where it all came from and being overcome by how much work it was to clean up after.
In our culture, we normalize stuff as love to our kids. As parents, is up to us to show our kids a different path.
The sad truth is that most people cannot remember what you gave them last Christmas. Most people cannot remember what they gave last Christmas. It seems to me that we are all participating in an endless cycle of mindless purchases.
So why do we tie ourselves into pretzels trying to impress each other with purchases?
Commercialization. The entire retail industry wants you to equate buying stuff with love.
If you think about, who really needs more stuff in their life? Most of us have way more stuff than we need and a lot of the time we don’t even want the stuff we are given!
Doing something for and with someone is way more memorable, personal, and enjoyable.
I cherish the memory of going on a hike with my kids (given to me as a mother’s Day coupon) or breakfast in bed (given to me as a birthday coupon) or an afternoon of games with my daughter (given to me as a Christmas coupon).
Be Creative
Some of our families best coupon ideas from over the years
- A hike together
- Doing the dishes without complaining
- A board game of the receivers choice
- A batch of homemade pierogies
- Money towards a tattoo
- Breakfast in bed
- A game of crib
- Money towards a video game
- A massage
- A day of video games together
Perhaps you notice a trend? Many of them are no cost and allow us to spend time on or with each other.
Some Advice
Speaking from experience, here are some things to keep in mind:
- Give your coupons an expiry date. This will help people who like to hoard things actually use them
- The issue can mark up a coupon as “used” once it’s been redeemed. This lets the recipient hang on to it for memories, if they want, and is very satisfying as the issuer.. it’s just feels like a job well done after the promise has been fulfilled
- Get artistic. You can design your own coupon or find printable ones online for free. Have fun decorating them or put them on fancy paper or write them into a handmade card.
The best part of giving coupons is that you can tailor them to the recipient in really personal and meaningful ways.
I hope this holiday season, you go forth and coupon!
If you enjoyed this post, please subscribe to the weekly MWM email.
Confidence
Published: 2026-09-25
It takes a certain amount of confidence to make big money decisions.
I recall discussing retiring early with my husband, who looked me square in the eyes and said “Just don’t make me become a Walmart greeter, k?”. By which he meant, make sure your plan is rock solid and we won’t screw our future selves.
Gulp. Cool, no pressure, right?
His fear was that our plan would fail and we would have to go to back to work doing something we hate. My fear was that we would live a life of austerity but then not save up enough fast enough to retire early in a significant way. I did not want to live a life restricted in my 30s and 40s only to realize I only shaved 5 years off of my retirement date.
A Progression of Planning
I’ve used different systems over the years to motivate and guide our big money decisions. Having a plan that is mapped out by way of a spreadsheet has been my guiding light and essential to achieving our money goals.
The Debt Busting Years
In our debt repayment years, I was obsessed with Microsoft Money. This product no longer exists, but it was fantastic! Not only did it track our budget, it graphed all our debt repayment schedules over time, making it easy to see at glance exactly when we would be debt free. It also let us run scenarios, like what would happen if we upped our mortgage payment by $50 a week.
Having the ability to run scenarios made it easy to build a plan with my husband. Seeing the impact from paying off debt faster in terms of saving time and interested charges was very motivating. We were happy to lock in a spending plan that got us to our goal faster.
Want to build your own debt busting plan? Check out my Debt Busting section on my Handy Links page for online tools to track and run scenarios on paying down debt. Drop me a comment if you try it and let me know your impression.
The Saving Years
After our debt was handled, we transitioned to our saving years. I built a simple spreadsheet to project at what age we would hit our “number”.
If you are into FIRE (Financial Independence, Retire Early), you might already have a “number” that you are working towards. In FIRE, your “number” is a target amount in savings (a.k.a your nest egg) that is big enough to to cover your daily expenses from your investment gains.
In our debt busting years, we followed the Life of Pie method, meaning we had been saving 10% along side paying down debt with at least 15% of our net income. This meant we had a small nest egg already accumulated. This was my “ground zero nest egg” and which become seed money for my spreadsheet calculation. I then mapped for every year how much we would have based on 7% investment growth with a monthly savings rate of $2250. Our safe drawdown rate is 4% of our nest egg. After setting up our base case, I copied the table and made versions that showed how much faster we would reach our number with a savings rate to $3000, $4000, etc.
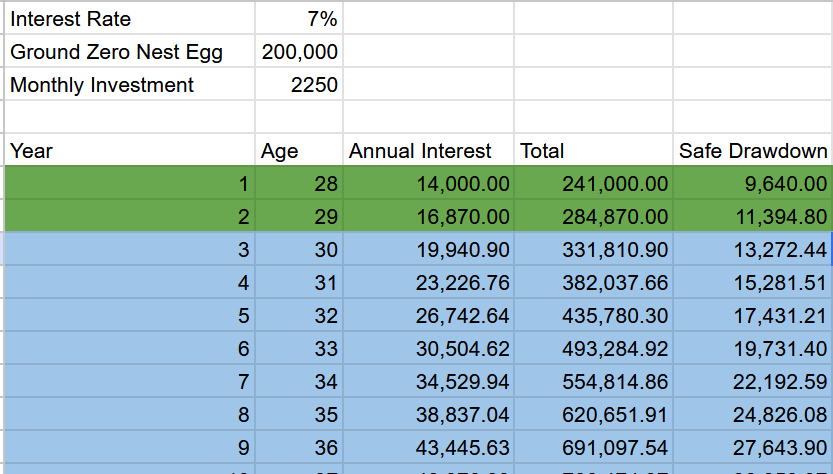
Seeing the year we should theoretically be able to leave our day jobs was very motivating! It still didn’t feel real, but we knew the numbers on the page couldn’t lie.
It’s worth noting that in our saving years, we adjusted the Life of Pie method and accelerated our savings rate, sometimes as high as 50% of our income. If you don’t care about retiring early, this is not something you need to worry about at all! Just follow the Life of Pie method, and you will be totally fine with a pretty fantastic life. But if you are FIRE curious, I highly recommend reading The Shockingly Simple Math Behind Early Retirement by Mr Money Mustache. This blog post changed my life! Then go ahead and devour the rest of his blog. It’s well worth the read!
Now a days there are much more sophisticated tools online that make my simple little spreadsheet look basic. If you are interested in trying some out, see an investment calculator called Smartasset, linked under my Handy Links under Investing, or the web app Projection Lab, linked under my Handy Links under Wealth Management. While these are very cool, you could also keep it basic like we did, and just build yourself a tidy little spreadsheet.
The FIRE Years
We are now in our FIRE years. We’ve retired early and now we need to manage and protect the nest egg so that it lasts into our traditional retirement years and beyond.
This is the probably the most nerve wracking phase. In order to pull the trigger and leave our day jobs, we REALLY needed to see the numbers mapped out.
To help us, about 3 or 4 years before we planned to retire at 45, I built an uber spreadsheet, which I will call our Projections spreadsheet. We still use it to this day to make big (and scary) money decisions.
Our Projections file maps out our annual income and expenses from the current year until we’re 95 years old. It also maps out our annual net worth, tracking assets and liabilities over time. Our expenses increase every year based on value for inflation, which we’ve set at 3%. Our investments grow annually based on a value for ROI (return on investment), which we’ve set at 7%. It also shows us the impact, over time, of drawing from our investment accounts, which will give us income now that we don’t have day jobs.
Our file is both simple and not simple, at the same time. It’s evolved heavily over the years, especially as we came closer to leaving our jobs. For us, it’s a guiding light that lets us know we’re gonna be okay. It’s also a tool that we call on when we have to make big life decisions. For example, when we returned to Canada, we used it decide where we could live and keep on budget. In this past year, we used it help us decide how much we could afford to spend on travel. We can’t account for everything in our monster of a spreadsheet, but we can get pretty darn close. That being said, FIRE is not for the faint of heart! If you want to FIRE, you need to know your numbers inside and out.
Bone Shaker
Last week we received some impactful news. Our tenant, who was renting out our “forever” home while we were in Australia, has given their notice. When we returned to Canada, we made a big life decision not to evict them immediately and continue renting while we spent time in another part of the country. Losing renters means that we are losing a revenue stream that helped offset some (not all) of the carrying costs for us to keep that property. In our dream scenario, our tenants would have stuck around for another year. With the big news, we need to re-assess our life plans going forward.
Queue the panic alarms? Actually, not at all. Sure, the news is a bit stressful, mostly as an interruption in the status quo of our lives. But we have a baseline plan, and now we just need to review and adjust accordingly. So we dusted off our trusty Projection spreadsheet and mapped out what this means for us financially, based on what we know today. And guess what? We should be okay. Our Projections have given us the confidence to know that we don’t need to rush into any panic based decisions. We will want to make some adjustments over the next 5 to 10 years and next year we won’t plan a big vacation like this year, but that doesn’t feel like a great sacrifice right now.
Confidence (Question Mark)
Where does confidence come from? To be clear, even with our spreadsheets and our life planning, it’s not all smooth sailing all the time. We still can get queasy stomachs about what the future will hold. But all we can do is make the best decisions we can with what we know today. That’s all any of us can do, really. For us, confidence comes from being organized, disciplined, and based on real numbers that make sense.
What’s Your Take?
Have you had to deal with a big financial change? Did you have a system in place? Were you able to lean on an emergency fund? Drop me a comment or an email, I would love to hear what you would do!
If you enjoyed this post, please subscribe to the weekly MWM email.
Oh the places you will go
Published: 2026-09-18
We travelled a lot this year. So far, I’ve taken eleven trips. These have all been within the province and the budget for each has varied. I have one more local trip I’m taking this weekend and then we will end our year with la pièce de résistance: a trip to Sweden where we will watch the WFTDA roller derby championships!
As I am writing this, thirteen trips sounds extreme to me. It’s certainly the most I’ve ever travelled in one year for personal entertainment. I suspect we will calm down our travel plans next year, but who knows! This year we focused on doing a lot of roller derby activities which kept us busy most weekends over the summer season.
How to Think About Vacations
Vacations shouldn’t take you by surprise and you shouldn’t take on debt for travel. You are in charge of deciding how many trips you take, where you go, and how much you will spend.
Here is how we approach vacation spending.
- We allocate vacation spending in our monthly budget This has been our system for the past 30 years. In our traditional earning years, we would move a budgeted amount, for example $200 a month, to a separate account that I lovingly referred to as our “slush fund”. Now a days, we work a little differently, but for most people, I highly recommend a separate spot to stash earmarked cash. Our slush-fund account held house money intended to pool over time for large expenses like vacations, annual insurance bills, and Christmas. How much we had sitting in each “pot” of our slush fund was tracked within our budget. This system gave us predictability, stability, and an upper limit to what we could spend.
Predictability: We transferred money every month, without fail from our joint daily spending account to our slush fund account. It was a “bill” that we paid ourselves. If we didn’t spend it all in one year, it would roll into the next year to give us a bit more spending power, if we wanted it. Our system kept our money management simple and boring (which is the goal!).
Stability: Our monthly transfer meant a slow and steady drip of money into our pool. The monthly amount was decided once a year, during a money talk. We reviewed our income and expenses and set out all our planned spending for the upcoming year. The amount we allocated to vacation was based on what our household could afford monthly and it fit within on our total life expenses of 25% net income.
A Ceiling: Our system made it very easy to know when we could afford a trip, if ever. Instead of making life “exciting” and just deciding we deserved a vacation as we felt like it, our system insulated us from making choices based on FOMO. We did not “stretch ourselves” and there was no “we will figure it out later” mental gymnastics. We had the money that we had and it would only go so far. If we could afford $200 a month for vacations, the math was simple, that’s a max of $2400 a year for vacation spending. - We set special budgets for special occasions At a monthly money talk last last year, well before the travel season was upon us, we decided together that we wanted to dedicate more to travel this year. It was our first year together as retired and we wanted to spend more time focusing on roller derby events. So we looked at what we felt we could afford and allocated two extra pots of money. These are considered one time “special spending” budgets. The money was from surplus cash, rather than our monthly budgeted vacation amount.
Pot 1:France TripLocal Derby Travel
I wanted to attend MRDA championships in France. It ticked the box in which we like to double up derby destination travel with fun experiences and going to France is on my bucket list. So, I pencilled a special budget line item for a trip. However, as we approached the travel season and during one of our monthly money talks, my husband had a counter proposal: rather then blow so much money on one trip, we should spread our budget over a lot more short and local trips, giving us a heck of a lot more derby experiences. I came around to the plan and I figure we are simply deferring a France trip to a future adventure.
Pot 2: Sweden Trip
This will be a ten day trip that we are both looking forward to! We are gong to the 2026 WFTDA Roller Derby Championships and padding a few extra days for sightseeing. Would I have thought to go to Sweden otherwise? Probably not, but that’s the fun of bundling travel with derby. We see corners of the world we would not otherwise have visited. I had assumed that because we no longer had day jobs, it would be “easy” to spend several weeks overseas. But two things worked against us: 1) vacationing is not cheap! For a multi week trip, I think I would need to be more creative to try and live like a local rather than a tourist 2) somehow we are still really busy! We have life stuff happening at home which didn’t lend itself for us taking a longer trip.
The Best Vacation is One You’ve Already Paid For
I like planning stuff and we both really like tracking stuff.
- Set your budget ceiling. Either from your pooled vacation money or from a special pot of “extra” funds that you already have on hand.
- Build your budget! Planning the trip is (for me) the super fun part. I build a spreadsheet that lays out your itinerary, when you depart and return, which calculates your total days of travel.
I always include a few standard categories:
EV Charging (if driving) or Flights – based on how many times we figure we will need to supercharge our car or a google flight search
Accommodations – I use a guesstimate rate for accommodations, based on a somewhat educated guess as to where we are going, and times it by the total days. In the example below, I assumed $100 per day for hotel or an airbnb.
Food & Drink – Similar to accommodations, I assume a daily rate of $75
Events & Attractions – For a short / targeted trip, you might only have one event you are attending. You can either build your budget around that (i.e. the cost of a pair of tickets to the event) or, if it’s a trip where we want to sight see, I’ll just set a daily rate of $50-$100 (best guess) to have something to stay within.
Land Travel – Typically required for sightseeing trips. This might be a rental car, local transit, or ride services.
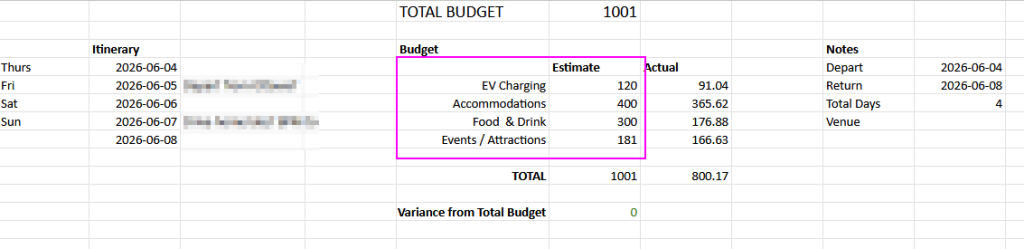

3. Decide if you can afford it. This is a big one and you must not skip it. At this point, we have not yet committed to taking the trip. Will the projected budget for the trip fit within our budget? For example, maybe flights are really expensive. If you are working from special budget of extra money, maybe you can allocate some of your vacation to cover the gap. Otherwise, the trip is probably a no go. And that’s okay! It’s far better to realize if you can afford a trip before you start booking stuff, rather than dealing with a debt hangover afterwards!
4. Book Stuff! Once you know you can afford it, you have the green light to book stuff! I like to copy past links and screen shots of my flight and accommodation booking into my spreadsheet so everything is in one place. As you pay for stuff, track your actual spending. Being over budget in one category is not a big deal, as long as it fits your total trip budget.
5. Let the count down begin! Now that everything is booked, you get to sit back and anticipate how much fun your next adventure will be!
6. Enjoy your fully funded guilt free trip! There is nothing as good as guilt free travel. Having everything paid for ahead of time means you will enjoy being in the moment, without a foreboding feeling of a looming debt hangover.
7. Post trip stuff – As I mentioned, we like to track stuff. So we do keep track of our travel spending. After a trip, we ensure the money we spent during travel is tracked in the Actual column of our budget sheet, so that we can keep ourselves accountable. Tracking our spending also helps us with our guesstimates for planning future trips.
Rinse and Repeat
And that’s how we plan all our trips! It’s a simple system and it’s easy to replicate. It also keeps us within a spending limit. And sometimes, it helps us feel good about turning down opportunities. Even with so much travel this year, I did turn down three other travel opportunities, solely because it wasn’t in our plan and I couldn’t afford it. And that’s totally okay! We all have limited funds and we all have the power to choose what we do with them.
If you enjoyed this post, please subscribe to the weekly MWM email.
Milestones
Published: 2026-08-28
It’s my anniversary today. My husband and I have been married 27 fun filled years. We have known each other for 32 years, which is wild to think about! Even more wild is how much I love my guy. Yup, we’re one of those gross couples who are still madly into each other and I see zero signs of that petering out any time soon.
I am a big believer in celebrating milestones. What I struggle with, sometimes, is deciding the best way to mark certain occasions.
The main issue is that, culturally, North Americans are not that creative. The norms for a celebration are typically food (going out to eat), drinks (ordering an expensive bottle of wine), and sometimes gifts (flowers, gold watches, etc.).
Diminishing Returns
When we were first married, we were crazy poor. Like, we slept on a twin mattress together poor. For, like, a year. So, it goes without saying, that celebrating every early milestone by eating out felt luxurious. For the first five years of our marriage, a milestone moment was probably the only time we sat down in a restaurant to eat. The only exception I can think of was our honeymoon where we lived it up and went out to eat nightly!
But after six or seven times around the sun, our mentalities started to shift. It was around this time that I graduated university, we started to earn double income, and I got my first career related job that was not in the service industry.
Suddenly we had choices. I don’t think we felt like we had money to burn, but we definitely could decide to eat out more, if we wanted to.
The funny thing is, though, that, by this time, we were used to cooking meals at home. All our meals, including bagged lunches for school and work.
With all that practice, we got pretty good at cooking. We learned how to make a steak better than the Keg. We learned how to make seriously delicious pizza. We learned how to make a melt in your mouth roast with Yorkshire pudding. We learned to make a Caesar salad exactly how my husband likes it.
We also were conscious of how much our time was worth. We were both still early in our careers, so while we had lifted ourselves above the poverty line, we were definitely not drowning in cash. We knew how many hours of work it took to buy something, including a sit down meal at a restaurant.
As time unfolded, we just didn’t enjoy going out to eat as much. We found we were paying a chunk of money for an experience that was kinda meh for food that was also kinda meh.
It was around this time that we finally looked at each other and admitted that we didn’t really want to go out to eat.
Finding the Fun
And so a new tradition was born. During this phase of our lives we had two young kids and both of us were working full time. Life was pretty exhausting. It meant that time together had become our most precious resource.
So, for many years, our new go to plan became Xbox and chill. Our game of choice? Dynasty Warriors
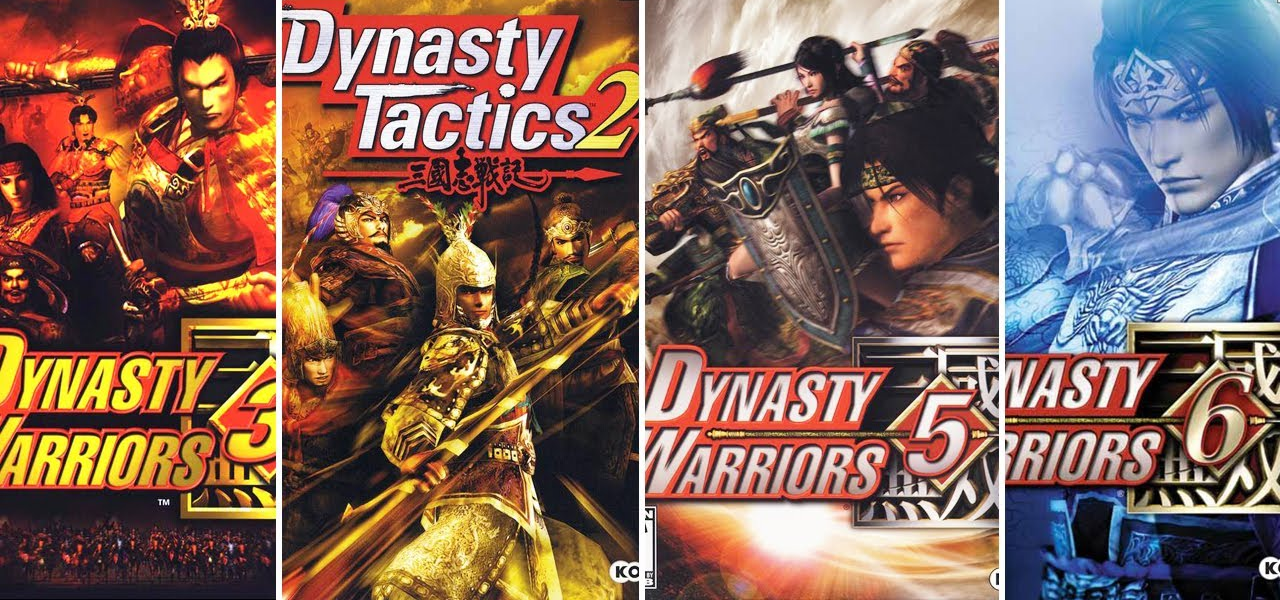
And so, for years, our go to anniversary fun was playing this game for hours upon hours. If a new version was out, we would “splurge” on the latest copy. We might order in something or make something and likely we would grab a bottle of sparkling wine.
Keeping Tradition Alive
I am a bit of a romantic and for my anniversary I have very much enjoyed giving my husband a “traditional” anniversary gift. I find it a little bit of a fun creative adventure to make or find a gift that he will enjoy made from the traditional material associated with that year. For our first anniversary, I wrote out our wedding vows on fancy hand made paper. For our 7th anniversary, I gifted him a Razer Copperhead computer mouse. For our 25th, I gifted him silver cuff links with the Cameron insignia on them.
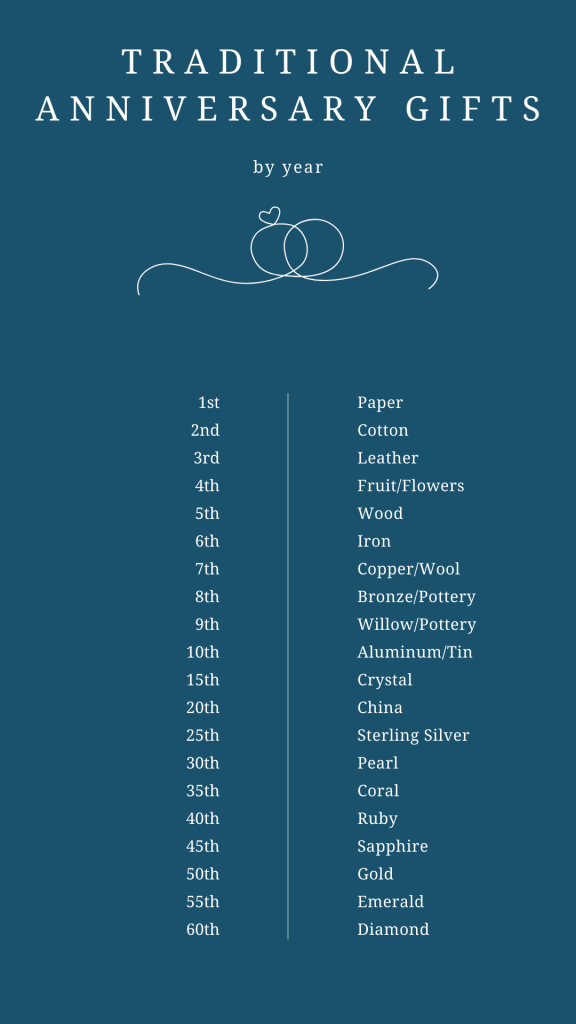
I confess that I don’t remember my gift from every year and I’m sure he doesn’t remember them either. For our 25th, I know we will cherish the big party we threw with our friends and the his & her tattoos that we designed for ourselves far more than some shirt jewellery that now sits in a box on his end table. Still, no regrets, because for me the act of giving a “creative” gift is fun.
You might be surprised to know that my husband rarely gets me an anniversary gift. I think perhaps it may have happened for first year, but I really couldn’t say for sure. And that’s totally fine by me. A gift is not expected or necessary. I don’t want flowers or mindless stuff. While I enjoy thinking of creative gifts to give, he does not. For him, I think having to give a gift under pressure of a date on a calendar is the polar opposite to joy. So, for us, it’s not a big part of how we choose to celebrate.
Evolution
Over the years we’ve built our own traditions. Most importantly, we have evolved our traditions as we’ve evolved as people.
We gave ourselves permission to be more intentional with how we spend our time and money while celebrating being together.
So tell me, how do you celebrate your milestones?